

Piere: Budget, Plan, Save analysis by Appwee
Managing money usually fails for a simple reason: the plan is made once, then forgotten when real life gets busy. Piere: Budget, Plan, Save takes a more practical approach by putting budgeting and automated saving in the same routine. After spending time with this finance app, I found its strongest idea is not flashy investment advice or complicated financial terminology. It is the attempt to make a money plan continue working after I have created it.
That distinction matters. A normal spreadsheet can show me where my money went, and a basic banking app can show transactions, but neither necessarily turns that information into a repeatable saving habit. Piere is designed around that gap. It is a free app from UniversTech, available for everyone, with optional in-app purchases ranging from $1.99 to $79.99 per item. Its current version is 6.2.2, and it requires Android 10 or later.
Automated saving is the feature that changes the experience
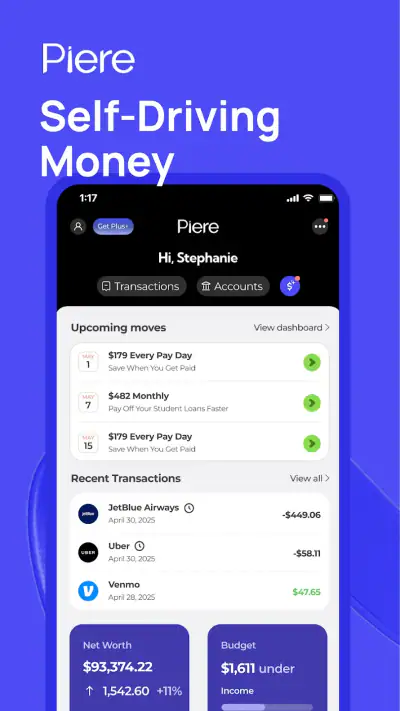
The central capability here is the combination of a budget with an automatic saving plan. I can think about upcoming income and expenses, decide what amount should remain available, and use the app’s automation to make saving less dependent on remembering to do it manually. In everyday use, that shifts the app from being a passive record of spending to being a planning tool.
I especially like this approach for people who already know they should save but repeatedly spend the available balance before transferring anything away. The problem is often not a lack of motivation. It is timing. When saving is postponed until the end of the month, unexpected food costs, transport, subscriptions, or small purchases can absorb the money. A planned automatic action gives saving a defined place in the month instead of treating it as whatever happens to be left over.
The useful idea is to make saving part of the budget before discretionary spending begins. That sounds obvious, but it changes how I read my available money. The balance is no longer simply “money I can spend”; some of it already has a job. This is a better mental model for building consistency than checking a banking balance and hoping discipline will appear.
The app’s store summary describes money management as something that can run on autopilot, but I would not interpret that as completely hands-off financial management. I still need to choose sensible targets, review the plan, and make sure the amounts fit my actual circumstances. Automation can reduce routine effort, but it cannot know whether a medical bill, a reduced paycheck, or a family expense is about to change the month.
What the workflow feels like in practice
I would begin by treating Piere as a planning workspace rather than a magic savings button. First, I would establish the expenses that must be covered, then separate flexible spending from money intended for saving. That order is important because an ambitious saving target can make a budget look successful while leaving too little for ordinary life.
Once the plan is realistic, the automation becomes more useful. Instead of opening the app every few days to make a fresh decision, I can use the original budget as a set of boundaries. The benefit is strongest when my income and recurring obligations are fairly predictable. In that situation, the app can support a repeatable rhythm: cover essentials, protect the saving amount, and use the remaining allowance without constantly recalculating everything.
A realistic example would be someone paid regularly who wants to build a buffer for annual expenses. They might set aside a manageable amount each pay cycle rather than waiting for a large surplus at the end of the month. When an insurance renewal or school expense arrives, the money is less likely to feel like an emergency because the goal was included in the plan earlier.
The less obvious advantage is psychological. A budget often feels restrictive when it only tells me what I cannot buy. An automated saving plan gives the budget a visible purpose. I am not merely cutting spending; I am moving toward a reserve, a planned purchase, or more breathing room. That makes it easier to accept limits on impulse purchases because the trade-off is clearer.
A practical routine for avoiding false progress
One habit I would recommend is reviewing the plan after an unusually expensive week instead of waiting for the end of the month. A budget can appear healthy for several days and then become unrealistic after a repair, a social event, or a cluster of small purchases. If I notice that the available spending amount no longer reflects reality, I would adjust the plan early rather than allowing an automatic saving target to create a cash shortage.
Another useful approach is to start with a deliberately modest goal. The purpose of the first weeks is to test whether the plan survives normal life, not to produce an impressive number. If the target is too aggressive, I may repeatedly interrupt the automation, which defeats the convenience. A smaller amount that continues reliably is more valuable than a larger amount that has to be cancelled.
I would also separate predictable annual costs from genuine long-term savings. A holiday, registration fee, or yearly subscription is not exactly an emergency fund. Treating those costs as separate goals gives the budget more honesty. Otherwise, I might think I am building financial security while the money is already committed to a known bill.
These are not complicated techniques, but they are where an automated budgeting app proves its worth. The technology matters less than the structure around it. Piere can make the routine easier to follow, but the quality of the result still depends on whether I give the automation a realistic job.
The best everyday scenario
The strongest fit is a person with regular income who has enough money to save but struggles to preserve it. Imagine a renter who receives a predictable paycheck, pays recurring household bills, and often reaches the end of the month wondering where the flexible spending went. They do not need a complex investment platform. They need a clear division between obligations, everyday spending, and money that should remain untouched.
For that person, Piere can become a monthly checkpoint and an automatic habit builder. At the beginning of the cycle, they can decide what amount is safe to save. During the month, the budget provides context for spending decisions. If a restaurant visit uses more than expected, the effect is easier to understand because it comes out of a defined category of available money rather than an invisible total balance.
The same workflow can help a couple who frequently discusses saving but never agrees on a repeatable method. A shared plan can make the conversation more concrete: which costs are fixed, which are flexible, and what amount should be protected first. I would still want both people to review the plan together, because automation should not hide financial decisions from anyone affected by them.
It is also useful for someone recovering from inconsistent spending habits. The app does not need to be used as a punishment system. A better approach is to choose one manageable saving objective and use the budget to observe patterns without trying to correct everything at once. That makes the process less overwhelming and gives the automation a clear, limited purpose.
Where the usual alternatives still have an advantage
A spreadsheet remains better for people who want complete control over every formula and assumption. It can be shaped around unusual income, complicated household arrangements, or detailed long-term projections. The cost of that flexibility is maintenance. I have to enter information, update formulas, and remember to inspect the file. Piere is more appealing when I value continuity over customization.
A bank’s own budgeting tools may feel more convenient because they sit close to accounts and transactions. They can be a good choice for someone who only wants a quick spending overview and does not want another finance app. Piere makes more sense when the main goal is a deliberate budget-and-saving routine rather than simply checking recent activity.
Cash-envelope methods are still excellent for people who respond to visible physical limits. Putting a fixed amount aside for groceries or entertainment can make overspending immediately noticeable. An app is less tangible, so it may not create the same restraint for someone who ignores digital reminders and balances. In that case, a simple envelope system could work better than any automated screen.
Dedicated investment apps are also a different category. Piere is suited to budgeting and saving behavior, not to replacing every financial service. If my priority is researching investments, comparing funds, or managing a portfolio, I would look elsewhere. Its value is earlier in the process: deciding what I can safely reserve before I think about more advanced financial products.
Trade-offs I noticed before recommending it
Automation creates convenience, but it also creates responsibility. A transfer or saving action that made sense when I created the plan may become inconvenient after an unexpected expense. I would not set a target and forget it indefinitely. A short review around each pay cycle is enough to catch obvious problems, especially after a change in income or a large one-off bill.
There is also a learning curve in translating real life into a budget. People rarely spend the same amount every month, and categories can become misleading if they are too broad. If I put every irregular cost into a single vague category, the plan may look tidy but tell me very little. The app works best when I use categories that reflect decisions I can actually make, such as food at home, eating out, transport, and discretionary purchases.
The free price makes it easy to try, but the presence of optional purchases means I would pay attention to which tools are included in the basic experience and which require an upgrade. I would not buy extras simply because the app presents them during setup. First I would use the core budgeting routine long enough to decide whether it genuinely changes my behavior.
Privacy and trust also deserve practical attention with any finance app. I would read the permission and account-connection screens carefully, use a strong device lock, and avoid connecting anything I do not need for my chosen workflow. Convenience is not a reason to hand over more access than necessary. That advice applies particularly to people who want only a manual budget and may not need broader connections.
The app is not the right choice for someone looking for personalized financial advice, debt negotiation, tax preparation, or investment research. It is also a weaker fit for people with highly irregular income unless they are willing to update their plan frequently. Automation is safest when the underlying assumptions are reasonably stable. With unpredictable earnings, a flexible manual method may prevent overcommitting money that has not arrived yet.
Who gains the most from Piere
I would recommend it first to people who have a clear reason to save and a repeated problem with following through. That includes building a buffer, preparing for a known yearly cost, or simply stopping the cycle of spending everything that remains in the account. The combination of planning and automation addresses the behavioral gap better than a screen that only reports past spending.
It can also suit beginners who feel intimidated by complex finance software. The basic question is easy to understand: what must be paid, what can be spent, and what should be saved? Someone who wants a gentle structure may appreciate that the app focuses on those decisions rather than requiring an advanced financial vocabulary.
More experienced budgeters may still find value if they want less manual repetition. However, they should not expect the app to replace a carefully designed financial system. If I already maintain detailed forecasts, multiple account rules, and specialized financial records, Piere would be most useful as a simpler daily layer, not necessarily as the only tool.
The app has reached over 50 thousand installs and holds a 4.5 average from 473 ratings, which suggests that its straightforward budgeting concept has found an audience. Those figures do not decide whether it fits my situation, but they do make it feel like an established option rather than an experiment with no visible user base. It was released on April 8, 2024, so I would still judge it mainly by how well its current workflow matches my needs.
My final take after using the budgeting approach
Piere: Budget, Plan, Save is most convincing when I use it to turn an intention into a routine. Its standout capability is automated saving connected to a budget, and that combination can remove the repeated decision of whether to save this month. For someone with predictable income and a tendency to spend first, that is a meaningful improvement over relying on willpower.
I would approach it with realistic targets, regular check-ins, and a clear distinction between emergency savings and money reserved for planned expenses. I would also compare its optional purchases with my actual needs before paying for anything. The app should support my financial habits, not become another subscription or task I avoid reviewing.
At no cost to download and with an Everyone content rating, it is approachable for a broad audience. Still, its best users are not everyone: they are people who want a simple, repeatable saving structure and are prepared to supervise the automation. If that describes you, I think UniversTech’s finance app is worth trying. If you need detailed forecasting, professional advice, or complete spreadsheet-level control, a more specialized alternative will probably serve you better.
Gallery
Piere: Budget, Plan, Save Pros and Cons
- Simple budgeting tools make it easy to track spending and plan ahead.
- Clear financial overviews help users understand where their money goes.
- Savings goals encourage consistent progress toward personal targets.
- Useful reminders can help prevent missed bills and planned payments.
- Clean interface is approachable for users new to money management.
- Some advanced features may require a paid subscription.
- Manual transaction entry can become time-consuming for frequent purchases.
- Budget accuracy depends on keeping income and expenses updated.
- Limited customization may not suit complex household finances.
- Users may need to review privacy settings before adding financial details.
Piere: Budget, Plan, Save Frequently Asked Questions
What is Piere: Budget, Plan, Save, and who is it designed for?
Piere: Budget, Plan, Save is a personal finance app designed to help users organize their money in one place. It can be useful for people who want a clearer view of spending, income, bills, savings goals, and overall financial progress. The app is especially appealing to users who prefer an automated overview rather than maintaining several separate spreadsheets or banking apps.
How does Piere connect to my bank and financial accounts?
Piere generally works by allowing users to connect eligible financial accounts so transactions and balances can be viewed together. Before linking an account, check whether your bank, card provider, investment platform, or loan company is supported in your region. You should also review the app’s privacy policy, permissions, and security information, since connected-account access involves sensitive financial data.
Can Piere help me create a budget and track my spending?
Yes, budgeting and spending organization are central purposes of Piere. After accounts are connected, transactions can typically be reviewed and arranged into spending categories, helping you identify where your money goes. The app may also support planning around recurring expenses, income, and financial targets. However, automatic categorization may occasionally need manual corrections to keep your budget accurate.
Is Piere free to download and use?
The app may be available to download without an upfront charge, but availability of features can depend on the current subscription structure, location, platform, or account type. Before creating a detailed financial plan, check the App Store or Google Play listing and the in-app pricing page for premium features, trial periods, renewal terms, and cancellation instructions. Prices and conditions can change.
Is Piere safe to use for managing personal financial information?
Because Piere can involve banking and other financial information, safety should be considered before use. Download it only from an official app store, use a strong unique password, enable available security protections, and avoid sharing login details with anyone. Read the provider’s privacy policy to understand how information is collected, processed, stored, and shared. The app should support financial organization, not replace professional financial advice.














